Independent MYGA Broker
Multi Year Guaranteed Annuity Advice From an Independent Broker
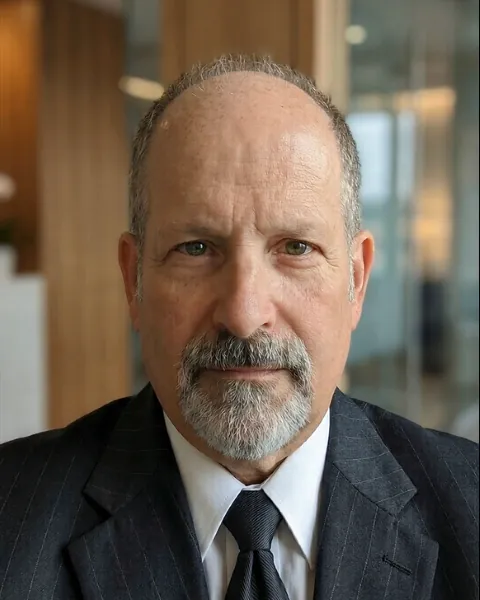
Ken Orenstein compares MYGA contracts from many top carriers, so you can see terms, withdrawal rules and surrender schedules side by side before you decide.
- Compare 3, 5, 7 and 10-year MYGA contract terms
- Independent broker, not tied to one carrier
- No-cost first consultation by phone, video or in person
Independent agency. No direct fee to you for annuity brokerage work.
Prefer to talk? Call (888) 315-3608
Request your no-cost MYGA review
Tell us a little about your situation. Ken Orenstein will contact you to talk through your options.
Why work with an independent MYGA broker
Many carriers, one conversation
Ken Orenstein represents many top annuity carriers, so you compare contracts instead of hearing one company's pitch.
Fixed terms you choose
MYGAs lock a stated interest rate for a set term, commonly 3, 5, 7 or 10 years. We match the term to your plans.
Principal protection focus
A fixed annuity is a conservative contract with no market exposure. Growth is tax-deferred until you withdraw.
Full disclosure before you sign
Caps, fees, free-withdrawal provisions and surrender charge schedules are reviewed in writing before any placement.
No direct fee to you
For annuity brokerage, Ken is paid a commission by the issuing insurance carrier, not by you.
Part of a bigger income plan
MYGAs are reviewed alongside Social Security, pension and other income layers so the whole plan fits together.
What a MYGA is and how we compare contracts
A Multi-Year Guaranteed Annuity is a type of fixed annuity. The insurance carrier states an interest rate for a set contract term, and your principal is not exposed to the market. Many people look at MYGAs as an alternative to a bank CD because gains grow tax-deferred until you take money out.
Because contracts differ a lot between carriers, the comparison matters more than the brochure. Ken Orenstein is an independent broker, so he lines up terms, withdrawal rules, surrender schedules and carrier financial strength side by side and explains the trade-offs in plain language.
- MYGA terms commonly offered at 3, 5, 7 and 10 years
- Free withdrawal provisions, often 10% of contract value per year, reviewed against your cash needs
- Surrender charge schedules compared across competing carriers
- Carrier financial strength reviewed using A.M. Best, S&P, Moody's and Fitch ratings
- 1035 tax-free exchange analysis if you hold an older fixed annuity
- Qualified and nonqualified funding, including 401(k) rollover and pension buyout money
- Typical buyers: retirees aged 65-73 and lump-sum recipients with $250,000 or more deployable
- Annuities are long-term retirement vehicles, not short-term investments
What happens after you ask for a review
You send the form
Share your lump-sum range and how you would like to meet. There is no cost and no obligation.
We talk it through
Ken Orenstein reviews your situation, time horizon and liquidity needs by phone, video or at the Flemington, NJ office.
You see the comparison
You get a side-by-side look at MYGA contracts and carriers, with terms, withdrawal rules and surrender schedules in writing.
Frequently asked questions
What does a MYGA review cost me?
The initial consultation is at no cost. For annuity brokerage there is no direct fee to you. Ken Orenstein is paid a commission by the issuing insurance carrier.
Is there a minimum amount?
Annuity placements typically start at $250,000 in investable assets available as a deployable lump sum. If you are below that, we can talk about other planning options.
What rate will I get?
Rates change with the market and vary by carrier and term. We review current contract terms together during your consultation so you see the actual numbers and the fine print.
Can I get to my money during the term?
Most MYGA contracts include a free withdrawal provision, often 10% of contract value per year, and a surrender charge schedule for larger withdrawals. We compare these before you commit.
Can I move an existing annuity into a new MYGA?
Possibly. A 1035 exchange can move an older fixed annuity to a current contract without triggering tax on accumulated gains. We run that analysis as part of the review.
Do you work outside New Jersey?
Yes. Insurance licensing covers NJ, NY, NC, MD, VA, DC and many other states. Meetings can be by phone or video, or in person in Flemington, NJ.
See your MYGA options side by side
Ask for a no-cost review with independent broker Ken Orenstein. You will see contract terms, withdrawal rules and carrier ratings in plain language before you decide anything. Call (888) 315-3608 or send the form.
- Compare 3, 5, 7 and 10-year MYGA contract terms
- Independent broker, not tied to one carrier
- No-cost first consultation by phone, video or in person
Prefer to talk? Call (888) 315-3608